

Purchase Loans
Adjustable-Rate Mortgages
Take advantage of lower initial interest rates with our exclusive Adjustable-Rate Mortgage option.
Take advantage of lower initial interest rates with our exclusive Adjustable-Rate Mortgage option.
Use your assets to help qualify for a home loan.
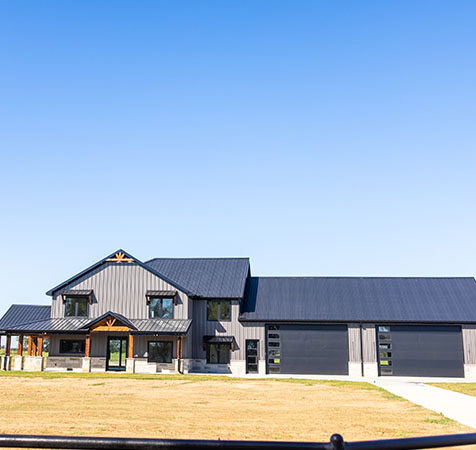
Financing a barndominium is easier than you think with Mortgage Center.
Leverage a family member’s strong credit to help you qualify for better loan terms.
A flexible home loan with great rates and terms. Very popular for homebuyers.
Tailored mortgage program for doctors and medical professionals with flexible terms.
Competitive fixed rates backed by Fannie Mae or Freddie Mac — predictable payments for the life of the loan.
Government-backed home loan with flexible credit guidelines and low down payment.
Mortgage financing for homes with small-scale farming or hobby farm use.
Lower down payments and PMI costs, with more flexibility to fund the purchase of your dream home.
Purchase and renovate your home with one convenient mortgage solution.
Financing for high-value homes with flexible terms and competitive jumbo mortgage rates.
Second-chance mortgage program for buyers rebuilding their financial future.
Mortgage solutions for condos that expand upon traditional lending guidelines.
Finance your build and permanent mortgage with one simple, streamlined construction loan.
Lower or eliminate private mortgage insurance (PMI) costs for greater monthly savings.
Low down payment financing for experienced buyers.
An exclusive VA home loan option for veterans, active-duty service members and eligible military families.
Purchase with no down payment and make homeownership more accessible. Perfect for First-time homebuyers.
Simplify your refinance with reduced paperwork.
Refinance your hobby farm property with flexible loan options designed for unique homes with agricultural use.
Get the most from your home’s equity with a maximum cash-out refinance. Use funds for home improvements, debt consolidation, or major life expenses.
Refinance your non-warrantable condo with flexible mortgage options that work for properties outside traditional lending guidelines.
This option can fund construction costs when you already own the land. This option can also pay off an existing land loan, if applicable.
Lower or eliminate PMI costs with our PMI Saver refinance option.
Ideal for borrowers who would like expanded qualifying options.
Saves you money if you’re active military or a veteran by allowing you to put no money down and avoid the cost of mortgage insurance.
Home equity loans are a great way to gain some extra cash for home improvements, debt consolidation, or other big purchases you’re looking to make. Like any loan, it’s important to understand how a home equity loan works before getting one.
Lock in today’s competitive rates and start saving on your mortgage. Our team offers fast, reliable options tailored to your needs.
Assumptions:
The information provided assumes the purpose of the loan is to purchase an existing single family detached home and will be used as a primary residence. The loan amount is $225,000 and the purchase price is $300,000. For Golden Jumbos, the loan amount is $900,000 and the appraised value is $1,200,000. The property is located in Oakland County, Michigan. There is an escrow account for property taxes and homeowners insurance. The rate lock period is 45 days and the assumed credit score is 780 or higher.
The monthly payment amount shown includes only principal and interest. The escrow for property taxes, homeowners insurance, flood and/or mortgage insurance if applicable are not included in the monthly payment amount. Your actual monthly payment will be higher with escrow account included.
The interest rates, APRs and points shown may change throughout the day due to varying market conditions. Rates are subject to change. To get more accurate and personalized results, please call 800-353-4449 to talk with a loan expert.
Securing a home loan is a vital step in the journey to achieving your homeownership goals. Loan offers from lenders can vary greatly, and it’s important to understand the costs associated with a mortgage loan, including the monthly payment, closing costs, and down payment amount.
A mortgage is a type of loan used to purchase a home. It’s an agreement between you, the borrower, and a mortgage lender to buy a home without paying all the money upfront. Instead, you pay the lender over time through a series of regular payments.
When you get a mortgage, a lender gives you a certain amount of money to buy a home. You have to pay back this amount (known as the principal) with interest over an agreed-upon period. Once your mortgage is paid off, you’ll have full ownership of the home. Keep in mind that if you don’t pay your mortgage, your lender can foreclose your property.
A loan estimate is a statement provided by a lender that gives you an estimated cost of your home loan. It includes an estimate of the interest rate, monthly payment, and other costs associated with the loan, such as closing costs, lender fees, and more. This estimate gives you a good idea of what to expect when you get your mortgage. It can also help you set a reasonable budget as you search for a home.
When it comes to home loans, there are several options available to accommodate your specific needs. Each loan type comes with different loan terms, interest rates, and benefits. Some common types of home loans include:
Different lenders offer different home loan rates based on the type of loan and your qualifications. The lender will consider factors such as your credit score, debt-to-income ratio, and employment history to determine your eligibility and interest rate.
Making a sizable down payment can also help you secure the best mortgage rate. Conventional down payments are usually 20% of the home’s value. However, the more money you put down, the less you’ll be paying in interest over time.
Lastly, discount points, or more simply, points, can help you decrease your rate. Points are bought by the borrower in an exchange for a discounted rate. Usually, points cost 1% of the loan value and reduce the borrowers rate by 0.25%.
Even small differences in rates and fees can cost or save you thousands over the life of your loan. Just as important is working with a team you trust.
At Mortgage Center, we’ve been helping homebuyers for over 35 years. With low rates, expert guidance, and a reputation built on service, we’re here to help turn your homeownership goals into reality.